Water Damage vs. Flood Damage in Kendall, Florida
Living in Kendall means enjoying everything South Florida has to offer, but it also means dealing with heavy rain, tropical storms, hurricanes, aging plumbing systems, and the possibility of flooding. For homeowners, one of the most important insurance questions is surprisingly simple:
Is water damage the same as flood damage?
From an insurance perspective, the answer is no.
The difference between water damage and flood damage can determine which insurance policy applies — or whether you have coverage at all. Kendall homeowners should understand this distinction before water enters their home, not after the damage has already occurred.
Water Damage vs. Flood Damage: What’s the Difference?
The easiest way to understand the difference is to consider where the water came from and how it entered the property.
Water damage generally refers to certain types of water that originate inside the home or result from a covered event. Depending on your homeowners insurance policy, examples could include a sudden plumbing leak, a burst pipe, an overflowing appliance, or water entering because a covered event damaged part of the house.
Flood damage generally involves water accumulating on normally dry land and entering a home from outside.
That distinction is extremely important because a standard homeowners insurance policy typically does not cover flooding.
What Is Considered Water Damage?
Imagine waking up in your Kendall home and discovering that a pipe underneath the kitchen sink suddenly broke overnight. Water has spread across the kitchen floor and damaged cabinets and other parts of the house.
Depending on the circumstances and terms of your policy, your homeowners insurance may provide coverage for some of the resulting damage.
Other examples of water-related losses that may potentially fall under homeowners insurance include:
- A sudden burst pipe
- An accidental plumbing leak
- Water released by a malfunctioning appliance
- Certain accidental overflows
- Rain entering after covered wind damage to a roof or window
Coverage varies considerably between policies. The cause of the water damage, exclusions, maintenance history, endorsements, and individual policy language can all affect whether your insurer covers the claim.
What Is Considered Flood Damage?
Flooding is different.
Under commonly used flood insurance definitions, a flood involves a general and temporary inundation of normally dry land affecting at least two acres or two or more properties, one of which is the policyholder’s property.
Flooding can result from conditions such as unusually rapid accumulation or runoff of surface water or the overflow of inland or tidal waters.
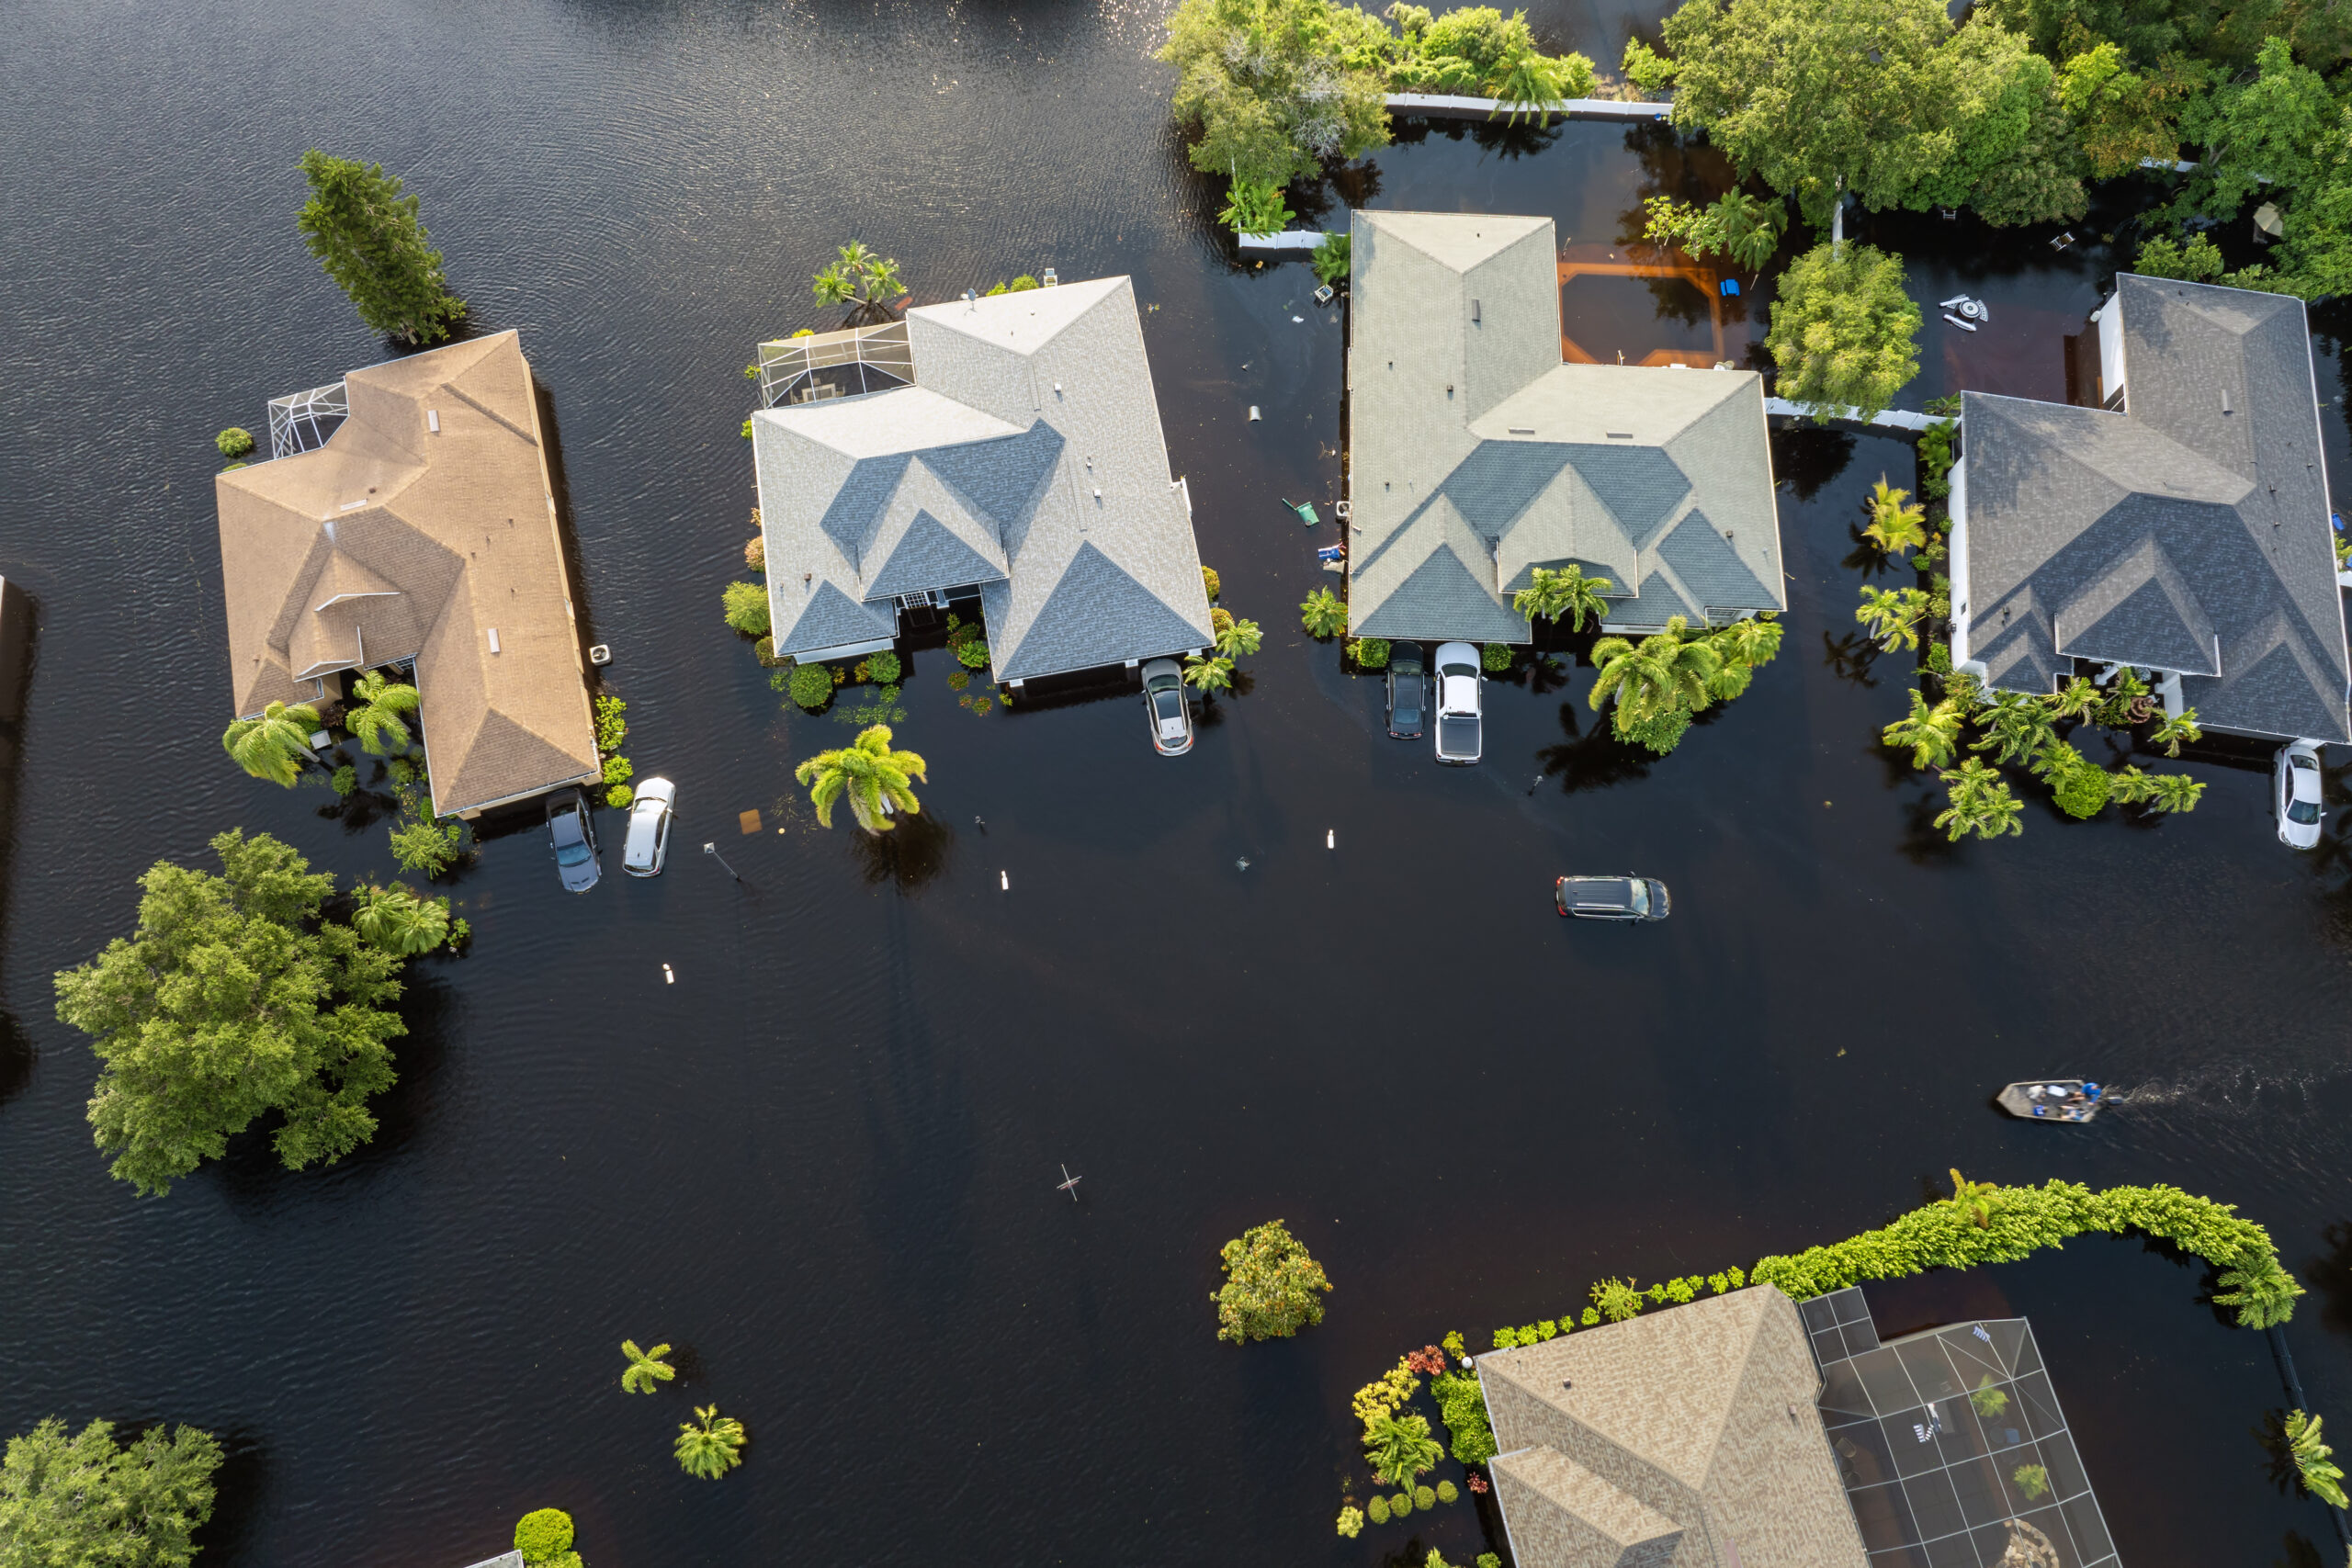
For a Kendall homeowner, think about a severe South Florida rainstorm that overwhelms drainage systems. Water begins accumulating on streets and surrounding properties. The outside water rises and eventually enters your home through a doorway or another low point.
That is very different from a pipe bursting inside the house.
Why This Matters for Kendall Homeowners
Kendall residents don’t have to live directly on the ocean to face flood risk.
Florida’s combination of intense rainfall, storms, and relatively low, flat terrain creates flood exposure throughout the state. Flooding can occur outside areas traditionally viewed as high-risk flood zones.
This is one reason homeowners should not assume that living outside a high-risk flood zone means flood insurance isn’t worth considering.
A severe afternoon storm can dump significant amounts of rain in a short period. If drainage cannot handle the water quickly enough, streets, yards, and surrounding areas can accumulate water.
If that rising outside water enters your house, your homeowners policy may not provide the protection you expected.
Does Homeowners Insurance Cover Flooding in Kendall?
Typically, no.
Most homeowners insurance policies do not cover damage caused by flooding.
Flood protection generally requires separate flood insurance, although some private insurance companies may offer flood protection through an endorsement or another coverage option.
Without additional flood protection, homeowners could face a potentially costly insurance gap.
A Kendall homeowner could have a homeowners policy with substantial dwelling coverage and still discover that the policy excludes damage caused by rising floodwater.
That’s why homeowners insurance and flood insurance should serve as two different pieces of a property’s overall protection.
A Simple Kendall Example
Consider two neighboring homes in Kendall that experience water damage during the same week.
Home A: Broken Pipe
A pipe suddenly bursts inside the house and causes significant water damage to the flooring, walls, and cabinets.
The homeowner’s insurance policy may cover the resulting water damage, depending on the policy’s terms, deductible, exclusions, and circumstances surrounding the loss.
Home B: Heavy Rain and Rising Water
A major storm produces intense rainfall across Kendall. Water accumulates outside, covers neighboring properties and streets, and eventually enters the house.
The standard homeowners policy would typically not cover the flood damage.
A separate flood insurance policy may provide coverage, subject to its terms and limits.
Both homes suffered water damage.
But from an insurance standpoint, the source and circumstances of the water can completely change which coverage applies.
What About a Roof Leak During a Storm?
This is where the distinction can become more complicated.
Suppose strong winds damage your roof during a storm and rain enters through the damaged portion of the roof.
Depending on the circumstances and your policy, your homeowners insurance may cover the resulting interior water damage.
Now imagine that the same storm causes water to accumulate outside your house. That water rises from ground level and enters through your front door.
That could constitute flood damage instead.
The same storm can therefore potentially cause different types of insurance losses.
What About Sewer and Drain Backups?
Homeowners should also pay attention to sewer and drain backups.
A standard homeowners policy may not automatically cover water backing up through an outside sewer or drain. Some insurers offer separate water-backup coverage through an endorsement.
Reviewing your actual policy can help you understand this coverage instead of assuming every type of water damage receives the same protection.
What If My Home Isn’t in a High-Risk Flood Zone?
Flood insurance may still be worth considering.
Flooding isn’t limited to properties located in the highest-risk FEMA flood zones. Heavy rainfall, overwhelmed drainage, and surface-water accumulation can affect properties outside those areas.
The Florida Office of the Insurance Consumer Advocate notes that approximately 25% of flood claims occur in low-risk areas.
That makes the question less about whether your Kendall home is “in a flood zone” and more about whether you’re financially prepared if outside water enters the property.
How Much Damage Can a Small Amount of Water Cause?
It doesn’t necessarily take several feet of water to create an expensive problem.
According to Florida’s Office of the Insurance Consumer Advocate, just one inch of water can cause up to $25,000 in damage to a home.
Water can damage flooring, drywall, cabinets, appliances, electrical components, furniture, and personal belongings.
Even relatively shallow flooding can therefore become a major financial loss.
Homeowners Insurance and Flood Insurance Can Work Together
For many Kendall homeowners, the goal isn’t choosing between homeowners insurance and flood insurance.
It’s understanding what each type of insurance protects.
Homeowners insurance may protect your home against various covered events, including certain types of sudden and accidental water damage.
Flood insurance specifically protects your property against covered flooding.
Having one does not necessarily mean you have the other.
NFIP vs. Private Flood Insurance
Kendall homeowners may have more than one option when shopping for flood insurance.
FEMA administers the National Flood Insurance Program (NFIP), which provides flood insurance to homeowners, renters, and businesses in participating communities.
Florida also has a private flood insurance market. Private insurers can offer different types of flood policies, and certain private policies may provide coverage or options beyond those available through a standard NFIP policy.
The right option depends on the property, desired coverage, limits, deductible, and other factors.
Don’t Wait Until a Storm Is Approaching
Kendall homeowners should consider flood insurance well before a hurricane or major rain event appears in the forecast.
New flood insurance policies may include a waiting period before coverage takes effect. For example, NFIP policies generally have a 30-day waiting period, although certain exceptions apply.
Waiting until a tropical system approaches South Florida may therefore be too late.
Questions Kendall Homeowners Should Ask
When reviewing your homeowners and flood protection, consider asking:
Does my homeowners policy cover sudden and accidental water damage?
What water-related exclusions are in my policy?
Do I have water or sewer backup coverage?
Do I currently have flood insurance?
What are my flood insurance dwelling and contents limits?
What deductible would apply?
Would an NFIP or private flood insurance policy better fit my property?
Understanding these details now can help prevent unpleasant surprises after a loss.
Protect Your Kendall Home Before the Water Rises
Water damage and flood damage may look similar when you’re standing inside a wet home, but insurance companies can treat them very differently.
A burst pipe inside your Kendall home may fall under homeowners insurance, while rising water entering from outside may require flood insurance.
Knowing the difference — and having appropriate coverage in place — can make a major financial difference after a severe South Florida storm.
Choice One Insurance can help Kendall homeowners review their existing homeowners coverage and explore flood insurance options to identify potential gaps before a loss occurs.
For more information about homeowners and flood insurance in Kendall and throughout South Florida, contact Choice One Insurance at 305-252-1873 for a personalized insurance review.
Frequently Asked Questions About Water and Flood Damage in Kendall
1. Does homeowners insurance cover flood damage in Kendall, Florida?
Generally, standard homeowners insurance does not cover flooding. A separate flood insurance policy or qualifying endorsement is typically needed.
2. What is the difference between water damage and flood damage?
Water damage may come from inside the home, such as a burst pipe, while flood damage generally involves rising or accumulating water entering from outside.
3. Do I need flood insurance if my Kendall home isn’t in a high-risk flood zone?
Flood insurance can still be worth considering. Heavy rainfall and drainage issues can cause flooding outside designated high-risk flood zones.
4. What happens if heavy rain causes water to enter my Kendall home?
Coverage depends on how the water entered. Rising surface water is generally considered a flood, while rain entering through storm-damaged portions of the home may receive different treatment.
5. Does flood insurance cover personal belongings inside my Kendall home?
Flood insurance may provide coverage for eligible personal belongings, depending on the policy. Building and contents coverage can have separate limits, deductibles, and exclusions.
Visit Our Other Interesting Pages
Auto insurance
Homeowners insurance
Car insurance inflation costs in Miami, Palmetto Bay & South Miami
Choice One Insurance
Affordable auto insurance in South Miami Heights